Are you frustrated watching others make money with investment properties ?
Struggling to understand how they bypass personal bank limits ?
Or how they buy without a massive cash deposits?
Takes 60 seconds.
No fluff, just the exact company framework Michael used to make R500 000 in 12 months ,
and protect the profits from SARS.
Before we go further
Does What I say Work?
Watch what Hein has to say
THE STRUCTURAL CEILING
THE SYSTEM IS BUILT TO KEEP
YOU CAPPED
You probably believe the banking system is rigged to keep individual buyers capped at their affordability ceiling.
& You are right. They look at your personal income, draw a line, and tell you that is all you get, or worse yet, that you cant get anything at all!
But your asking the wrong questions.
The fear of remaining forever small is real, but the release is understanding, that this is a design flaw of the spectator and Landlord state, not a personal failure.
You are playing the wrong game... one which is designed for you to lose.
The bank and tax codes are heavily weaponized against buying in personal names, but they are a playbook for companies.
This Is Where I See
People Getting
It Wrong
If your property Investing is done in your personal name, you've already lost.
Most South African investors make one fatal, beginner mistake: They Buy property like consumers, not like Professionals.
On paper it feels simple. In reality, you've just invited SARS, creditors and the Master's Office into every deal you'll ever do, and here is what happens:
You hit the personal debt ceiling after 2 to 3 bonds and the banks cut you off completely.
You pay the maximum marginal tax rate of up to 45% on every cent of rental profit instead of corporate rates.
Your personal estate is exposed to massive Executor fees (up to 3.5% + VAT) and Estate Duty when you die.
If a tenant sues or a business venture fails, creditors can attach every single property you own.
You cannot transfer properties into an entity later without paying double Transfer Duty and Capital Gains Tax.
You end up loosing teh ability to bring in equity partners or passive investors cleanly.
SARS treats your personal property portfolio as an individual asset, stripping strategic tax write-offs.
The Master's Office freezes all your personal bank accounts and rental cashflows for months upon death.
WATCH BELOW
WHY I DON'T BUY IN MY OWN NAME
What happens if you keep buying in your own name?
Every additional bond you register against your personal ID reduces your credit capacity until you are entirely un-fundable by mainstream financial institutions in South Africa. The debt-to-income limits kick in rapidly, leaving you stranded with a tiny portfolio that drains your monthly cashflow through punitive personal tax brackets.
Attempting to unravel this later costs hundreds of thousands in restructuring taxes, conveyancing fees, and estate friction. Continuing down this road ensures your growing asset base creates an unpredictable liability structure with it's own set of challenges.
What People Say About Me
QUALIFICATION
Who Is This For
We have 3 types of people who come to us... If can you identify with these, you are in the right place.
Type 1 example
Anet: SALARIED, OWNS NO INVESTMENT PROPERTY... Yet
Your blocker is belief, not Desire. Your capable, smart and driven when you know how. You fear you cannot enter the market, but the release is flipping your first unit for a R100 000 profit without using your own money.
THE DIRECTORS ENTRY KIT
TYPE 2 EXAMPLE
THABO: OWNS 1-3 PROPERTIES, HIT AFFORDABILITY CEILING
Your blocker is not knowing, and it is fixable. You fear being stuck forever, but the release is knowing you can own a R31 million building with R0 of your own money through correct structuring.
THE DIRECTORS ENTRY KIT
TYPE 3
Johan : SELF EMPLOYED, A;SO OWNS NO INVESTMENT PROPERTY... Yet
Your blocker is your frustration at the system, not your ability to execute.
You're annoyed at not being able to get a mortgage as someone who is "self employed", but the release is buying your properties in a company name WITHOUT needing a mortgage.
THE DIRECTORS ENTRY KIT

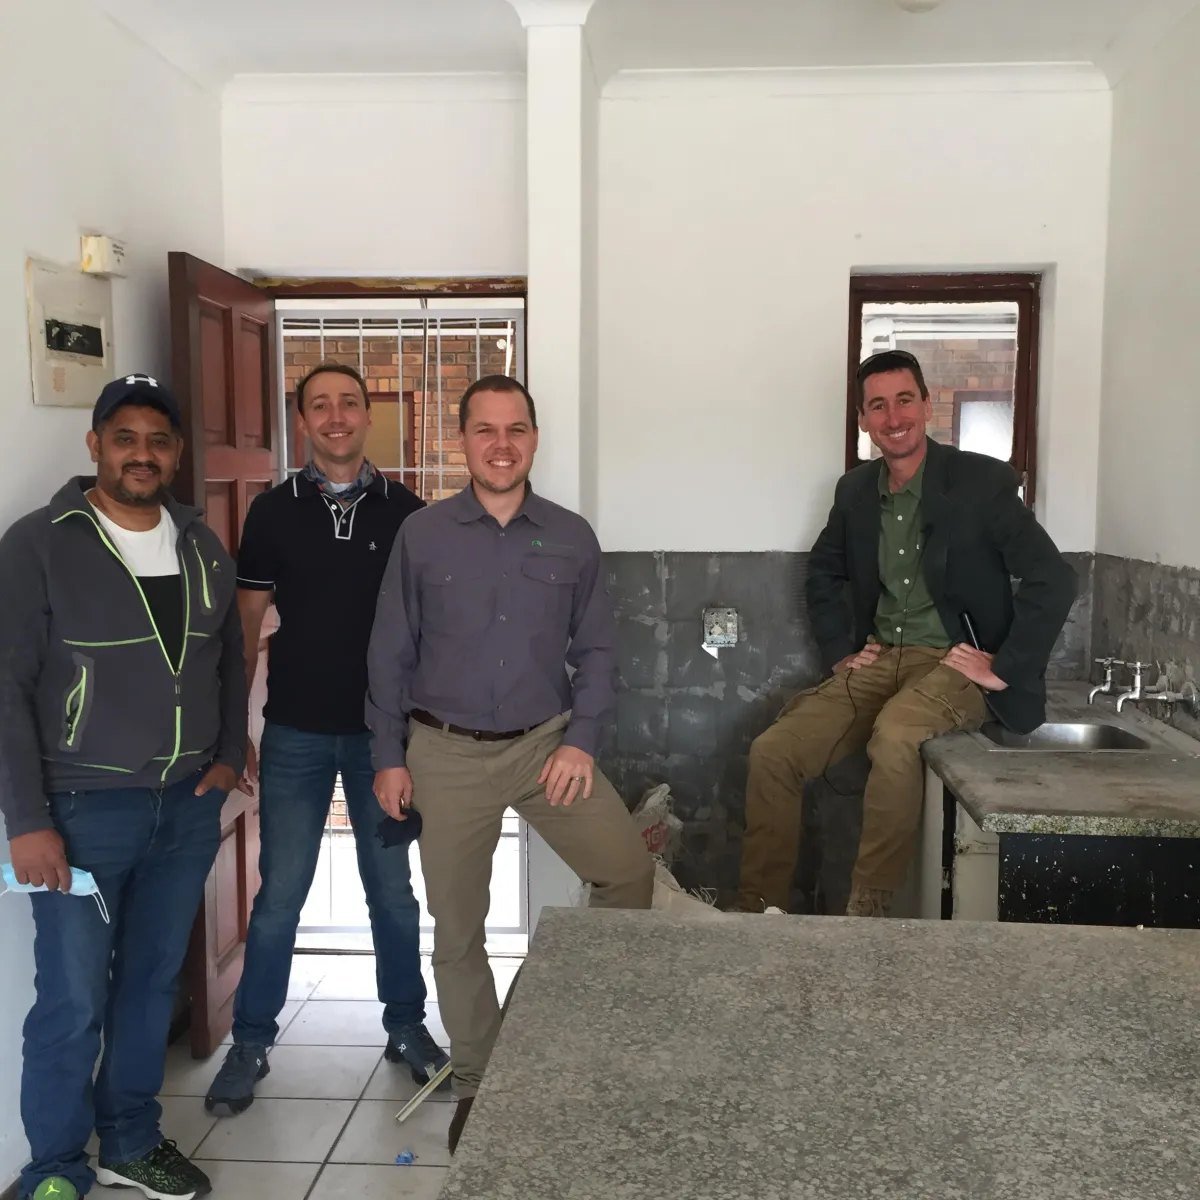
Michael | Portfolio Founder & Strategist
THE FOUNDER'S STORY
MORE FAILURES
THAN SUCCESSES
I will be completely honest with you:
By count, I have had more property failures than successes. By count.
But, this is also the truth:
By profit, my structured successes are 100x more successful than the losses!
Whilst 3 properties lost me R70K one year, 1 property netted me over R500K the very next year.
When I finally stopped chasing "hot deals" and started focusing entirely on legal and financial structureS, everything shifted.
Today, I own a R31 million building with R0 of my own money in it. Not because I got lucky, but because the acquisition was structured correctly from day one.
You can either learn these lessons the hard way through devastating and embarrassing losses, or you can learn the framework that makes the losses irrelevant and the wins exponential.
PS. The 70K losses were written off as Tax deductions the following year.
FAST-TRACK YOUR PROGRESS
Bypass 10 Years Of Failures
If you want to bypass 10 years of countless mistakes, Failures, countless mistakes, and the sleepless nights, then get your entry kit today.
Instant Download • 100% Free •
No 3-Year Financials Required
EXCLUSIVE FRAMEWORK • IMMEDIATE ACCESS
Are you ready to build a property portfolio without maxing out your own personal bank loans?
The wealthiest families acquiring premium real estate across Sandton and Camps Bay operate by a single sacred rule: own nothing, control everything. They do not tie up personal debt or put personal assets at risk.
What does the Entry Kit share with you:
- Estate Duty Immunity: The legal structure that prevents SARS from taking up to 25% of your wealth upon generational transfer.
- Section 13sex Tax Deductions: How to write off up to 55% of the purchase price on residential units to wipe out taxable income.
- Ironclad Asset Shielding: Ring-fencing properties so personal creditors and civil liabilities can never touch your family portfolio.
- Circumventing Personal Suretyships: The director borrowing protocol that unlocks institutional debt without pledging personal primary homes.
- Off-Balance-Sheet Expansion: Acquiring multi-unit portfolios where each company vehicle stands independently without credit contamination.
- The 3-Year Financials Bypass: Exactly how special-purpose property holding companies secure commercial bonds from Day 1.
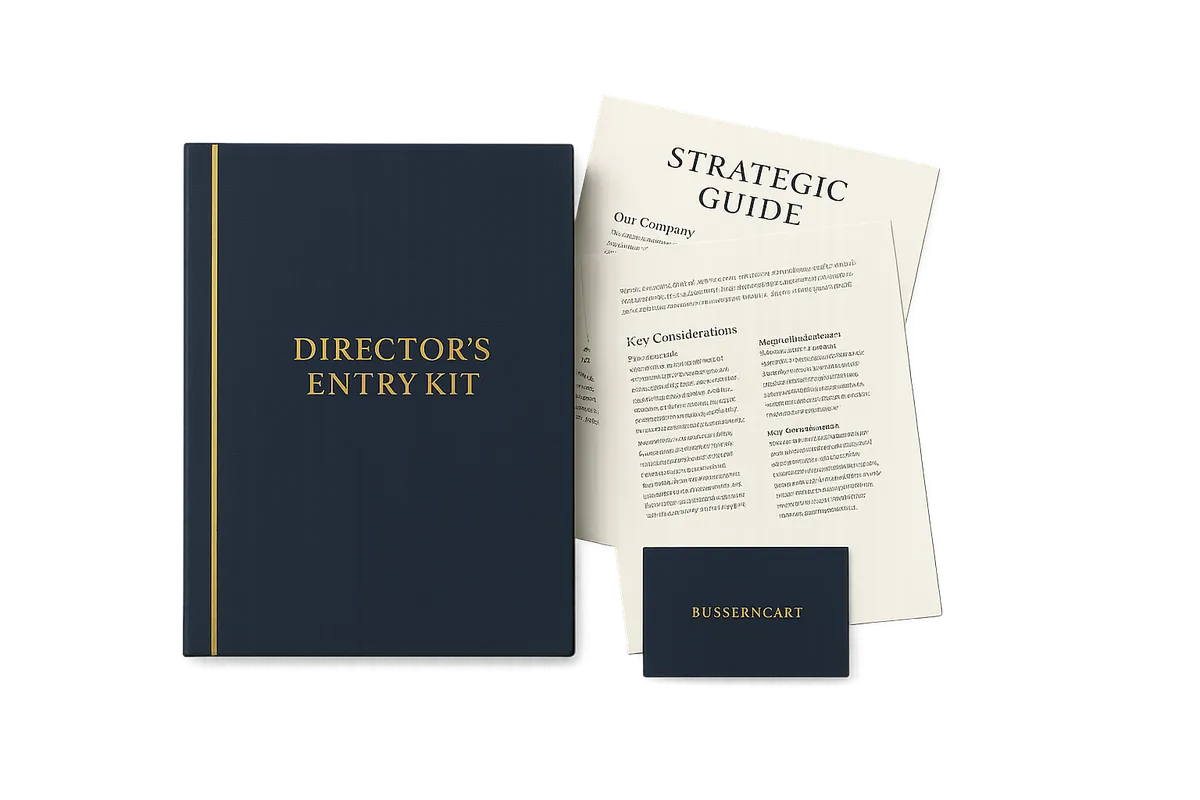
Drop your details below to immediately unlock the full Director's Entry Kit digital documentation, legal blueprints, and banking term sheets.
This protocol is completely free. No upfront consultation fees. Zero obligation to proceed.
Strategic Note on Estate Duty: Under the current SARS framework, transferring property out of personal capacity into an entity is 10x more costly once built. Structuring correctly from Day 1 is your fiduciary advantage.
CRITICAL DUE DILIGENCE
Frequently asked by serious investors:
How can a newly registered company buy property with zero financial track record?
South African banks underwrite company property transactions based on the director surety, lease cash-flow ratios, and underlying asset valuation rather than traditional three-year audited statements. Our framework shows you exact debt service calculation formulas banks require.
Why shouldn't I just purchase investment units in my personal name?
Buying in your personal name hits maximum marginal income tax rates (up to 45%), exposes all personal wealth to creditor litigation, and limits your bond exposure once debt-to-income caps are reached. Structuring inside a corporate entity isolates liability and caps base tax at 27%.
Will I still need to sign personal surety for the company bond?
During your initial commercial acquisitions, banks typically require limited personal surety. However, the blueprint outlines how to progressively transition debt covenants into standalone non-recourse facilities as your company asset base and debt-cover ratios mature.
What happens to teh existing properties currently under my personal bond?
The kit outlines safe asset-migration strategies, Section 42 company formation rollovers, and secondary refinancing methods to transition equity out of your personal balance sheet without triggering immediate prohibitive tax liabilities.
Do I need substantial upfront cash reserves before applying this model?
No. The system teaches leverage mechanisms, vendor financing structures, and joint venture syndication frameworks designed to fund deposits and acquisition fees using institutional criteria rather than personal savings.
How does SARS treat rental income and capital gains inside a (Pty) Ltd structure?
Rental net profits are taxed at the fixed corporate flat rate of 27%, with an effective Capital Gains Tax inclusion rate of 21.6%. Company expenses, management allowances, and operational deductions substantially reduce taxable thresholds compared to personal ownership.
Is this framework compliant with all South African bank lending criteria?
100%. Every structure, resolution document, and bank submission template strictly adheres to the National Credit Act, Companies Act 71 of 2008, and major commercial bank underwriting guidelines across South Africa.
How quickly can I review and deploy the Director's Entry Kit materials?
You receive instant digital access immediately after requesting the kit. The core executive briefing takes under 35 minutes to study, with all document templates pre-formatted for rapid implementation.
Stop sitting on the sidelines or buying property in your personal name
IN South Africa, If you are a property Spectator or a landlord -
Your are loosing the most
Engineered for South African investors ready to scale beyond personal balance sheet restrictions. 100% Free Instant Download.